For many Arizona homebuyers in Phoenix, Tucson, Chandler, and beyond, the choice between an FHA loan and a conventional loan is the most important mortgage decision they will make. Both can get you into a home. But the costs, requirements, and long-term implications are meaningfully different, and picking the wrong one can cost you thousands of dollars over the life of your loan.
This guide lays out the real differences between FHA and conventional loans in Arizona for 2026: what each one requires, what each one costs, and which loan type tends to make more sense depending on your credit score, down payment, and financial goals as an Arizona buyer.
Quick Answer: FHA vs. Conventional Loan in Arizona
FHA loans in Arizona are generally better for buyers with credit scores below 680 or limited down payment savings. FHA allows credit scores as low as 580 with 3.5% down and accepts higher debt-to-income ratios. The trade-off is mortgage insurance that stays for the life of the loan in most cases.
Conventional loans in Arizona are the better long-term choice for buyers with a 620 or higher credit score, especially at 680 and above, because private mortgage insurance (PMI) can be removed once you reach 20% equity, unlike FHA mortgage insurance.
For Arizona buyers using Home Plus down payment assistance, both FHA and conventional loans are eligible for up to 5% in down payment and closing cost help through the Arizona Industrial Development Authority (AZIDA). This program has no first-time buyer requirement and works in cities across the state including Phoenix, Chandler, Gilbert, Scottsdale, Glendale, Mesa, and Tucson.
FHA and Conventional Loans in Arizona at a Glance
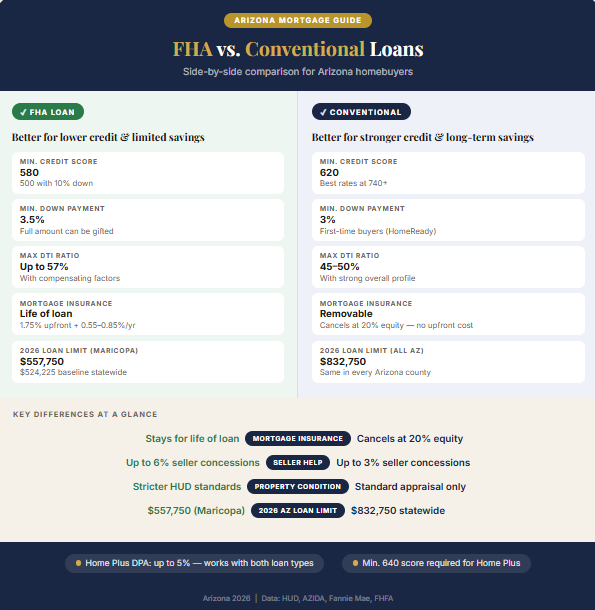
Before going into detail, here is a direct comparison of how the two loan types stack up on the factors that matter most to Arizona homebuyers in 2026.
- Min. credit score: 580 (3.5% down) or 500 (10% down)
- Min. down payment: 3.5%
- Max DTI: up to 57% with compensating factors
- Mortgage insurance: required for life of loan (if less than 10% down)
- 2026 loan limit in Maricopa County: $557,750
- Government-backed by HUD
- Min. credit score: 620 (best rates at 740+)
- Min. down payment: 3% (first-time buyers)
- Max DTI: 45-50% with strong profile
- PMI removable once you reach 20% equity
- 2026 conforming loan limit in Arizona: $832,750
- Backed by Fannie Mae or Freddie Mac
FHA vs. Conventional Loan Comparison Table (Arizona 2026)
| Factor | FHA Loan | Conventional Loan |
|---|---|---|
| Min. Credit Score | 500–580 | 620 (740+ for best rates) |
| Min. Down Payment | 3.5% (580+ score) / 10% (500–579) | 3% for first-time buyers; 5% otherwise |
| Max DTI Ratio | Up to 57% with compensating factors | 45–50% with strong profile |
| Mortgage Insurance | MIP for life of loan (if <10% down) | PMI removable at 20% equity |
| Upfront Insurance Cost | 1.75% upfront MIP | None |
| Annual Insurance Cost | 0.55%–0.85% of loan balance/year | 0.5%–1.5% of loan balance/year (varies by score) |
| 2026 Loan Limit (Maricopa) | $557,750 | $832,750 |
| Property Condition | Stricter appraisal standards (HUD guidelines) | Standard appraisal requirements |
| Gift Funds Allowed | Yes, entire down payment can be gifted | Yes, with documentation |
| Home Plus DPA Eligible | Yes | Yes |
| Best For | Lower credit, limited savings, higher DTI | 620+ credit, long-term cost savings, higher loan amounts |
How Credit Score Affects Your Choice

Credit score is the single biggest factor that separates FHA and conventional loan candidates in Arizona. Here is how the thresholds break down in practice.
Credit Score Below 580
At this range, FHA is your primary option among standard loan programs. FHA allows scores as low as 500 with a 10% down payment. Conventional loans are generally not available below 620. Before applying, it is worth taking 3 to 6 months to improve your score if possible, since moving from 579 to 580 alone changes your minimum down payment from 10% to 3.5%.
Credit Score 580 to 619
FHA is still the practical choice in this range. You qualify for 3.5% down with FHA, while conventional loans are not accessible. The mortgage insurance cost is higher than conventional PMI for strong-credit borrowers, but the lower barrier to entry makes FHA the clear path into homeownership.
Credit Score 620 to 679
This is the decision zone. You can now qualify for both FHA and conventional loans. FHA may still offer a lower rate, but conventional PMI can be removed later while FHA mortgage insurance on loans with less than 10% down stays for the life of the loan. If you plan to stay in the home for more than 5 years, running the total cost comparison matters here. Use a mortgage calculator to compare the long-term cost of each option at your actual credit score and loan amount.
Credit Score 680 and Above
Conventional becomes increasingly attractive. Rates improve, PMI costs drop, and the ability to cancel mortgage insurance once you hit 20% equity gives conventional a meaningful long-term cost advantage over FHA. At 740 and above, conventional typically offers the best available rates and lowest overall cost of the two options.
Credit score is not the only qualification factor. Your debt-to-income ratio, employment history, and the property you are buying all affect approval. A 680 score with a 50% DTI may still be steered toward FHA, while a 640 score with low debt and strong reserves may qualify cleanly for conventional. Always get pre-qualified to know your actual options.
Mortgage Insurance: The Biggest Cost Difference
Mortgage insurance is where FHA and conventional loans diverge most significantly on total cost. Understanding this difference is critical, especially for buyers who plan to stay in their home long-term.
FHA Mortgage Insurance Premium (MIP)
FHA loans carry two forms of mortgage insurance. The upfront mortgage insurance premium (UFMIP) is 1.75% of the loan amount, added to the loan balance at closing. On a $300,000 loan, that is $5,250 added to what you owe. The annual MIP runs between 0.55% and 0.85% of the remaining loan balance, divided into monthly payments.
For most FHA borrowers who put less than 10% down, MIP stays for the entire life of the loan. The only way to remove it is to refinance into a conventional loan once you have built enough equity, typically 20% or more. If rates are higher at that point, refinancing may not make financial sense.
Conventional PMI
Private mortgage insurance on conventional loans typically runs 0.5% to 1.5% of the loan amount per year, and the rate depends on your credit score and down payment. On a $300,000 loan with a 720 credit score, PMI might run $100 to $150 per month. The key advantage over FHA MIP is that PMI automatically cancels once your loan balance reaches 78% of the original purchase price, and you can request cancellation at 80%. Once it is gone, your payment drops permanently, without refinancing.
- FHA: Upfront MIP of $5,513 added to loan + approximately $150/month in annual MIP. If you stay in the home and never refinance, you pay MIP for 30 years: roughly $54,000 total in insurance costs.
- Conventional (680 score): No upfront cost + approximately $175/month PMI. PMI cancels around year 9 when you reach 20% equity: roughly $18,900 total in insurance costs.
- Conventional (740+ score): PMI is lower, around $100 to $125/month, canceling even sooner. Total insurance cost closer to $11,000 to $13,000.
- The difference between FHA and conventional mortgage insurance over a full loan term can exceed $35,000 to $40,000 for the same home purchase.
Down Payment Requirements in Arizona
Both loan types allow low down payments, but the programs and assistance available in Arizona make the practical difference smaller than the minimums suggest.
FHA Down Payment
FHA requires 3.5% down with a 580 or higher credit score. On a $350,000 home, that is $12,250. The full down payment can come from gift funds from a family member, which makes FHA attractive for buyers who have family support but limited personal savings. Sellers can also contribute up to 6% of the purchase price toward closing costs, reducing the cash you need at closing.
Conventional Down Payment
First-time buyers using Fannie Mae’s HomeReady or Freddie Mac’s Home Possible programs can put as little as 3% down on a conventional loan. That is $10,500 on a $350,000 home. Gift funds are also allowed. Buyers who are not first-time buyers typically need 5% down for a conventional loan. Putting 20% down eliminates PMI entirely from day one, which significantly reduces the monthly payment and total cost.
Arizona Home Plus Down Payment Assistance
Arizona’s Home Plus program through the Arizona Industrial Development Authority (AZIDA) offers down payment and closing cost assistance of up to 5% of the loan amount, and it works with both FHA and conventional loans. There is no first-time buyer requirement, and the assistance does not need to be repaid as long as you keep the loan for at least three years.
On a $350,000 home, 5% assistance means up to $17,500 toward your down payment and closing costs. For an FHA borrower who only needs 3.5% down ($12,250), Home Plus can potentially cover both the down payment and a portion of closing costs. For a conventional borrower using a 3% down program, it can do the same.
Home Plus requires a minimum credit score of 640 and the loan must be originated through an approved AZIDA lender. Income limits apply and vary by county. Verify current availability and eligibility requirements at the Arizona Industrial Development Authority. If you are unsure whether you qualify, a mortgage preapproval with a participating lender will confirm your options. Home Plus also works across many Arizona communities, from Phoenix and Chandler to Glendale and Surprise — see communities we serve to find yours.
Arizona Loan Limits: FHA vs. Conventional
One practical difference between FHA and conventional loans in Arizona is the loan limit. In 2026, these are the limits for a single-family home.
| Loan Type | Maricopa County | Pima County | Most Other AZ Counties |
|---|---|---|---|
| FHA | $557,750 | $541,287 | $524,225 (baseline) |
| Conventional | $832,750 | $832,750 | $832,750 |
For most Arizona buyers, the FHA loan limit is not a practical constraint. The median home price in Phoenix metro, Tucson, Mesa, Chandler, and Gilbert sits well below the FHA ceiling. However, buyers in higher-price neighborhoods like Scottsdale, Paradise Valley, north Scottsdale, or Arcadia may need a conventional loan to access the higher loan amount, or a jumbo loan if their purchase price exceeds the conventional conforming limit of $832,750.
Property Condition Requirements
FHA loans have stricter property appraisal standards than conventional loans. The FHA appraiser is required to flag and report health and safety issues, including peeling paint, broken windows, faulty electrical, missing handrails, water damage, and any structural concerns. The seller must typically repair flagged items before the loan can close.
This creates a practical issue in Arizona for buyers targeting older homes, fixer-uppers, estate sales, or properties that have been vacant or distressed. Sellers of those types of properties often prefer conventional offers because they carry less appraisal risk. If you are competing for a home in a hot market, a conventional loan offer can be more attractive to a seller even at the same price. This is especially relevant for buyers considering new construction homes in Arizona, where builder contracts and appraisal timelines can interact differently with FHA vs. conventional requirements.
Conventional appraisals still assess market value and condition, but the threshold for required repairs is lower. Minor cosmetic issues, aging systems that are functional, or deferred maintenance items that do not affect safety typically do not hold up a conventional loan closing the way they would an FHA one.
Which Loan Is Right for You? Common Arizona Buyer Scenarios
FHA’s more flexible credit requirements and capped MIP rates at lower scores make it the better starting point. Plan to refinance into conventional once your equity and credit improve.
FHA allows back-end DTI up to 57% with compensating factors, giving more room if you carry car loans, student debt, or other obligations alongside a mortgage payment.
FHA allows 100% of the down payment to come from a gift with proper documentation. It is the most flexible option for buyers relying on family contributions.
The ability to cancel PMI, lower long-term insurance costs, and competitive rates at 680 and above make conventional the smarter financial choice for most buyers in this range.
The permanent nature of FHA MIP is a long-term cost burden. If you plan to stay in the home for 10 or more years, conventional saves significantly more money over time even if the rate is slightly higher initially.
Properties with deferred maintenance or condition issues have a much smoother path through conventional appraisal than FHA. Sellers also tend to favor conventional offers in competitive situations.
Is FHA easier to get than conventional in Arizona? Yes. FHA accepts lower credit scores (580 minimum vs. 620 for conventional) and higher debt ratios, making it more accessible for buyers who do not yet have a strong credit or financial profile.
What are the FHA loan limits in Arizona for 2026? $557,750 in Maricopa County, $541,287 in Pima County, and $524,225 in most other Arizona counties. Conventional conforming loans go up to $832,750 statewide.
Can I buy a home in Phoenix with an FHA loan? Yes. Phoenix is in Maricopa County, where the 2026 FHA loan limit is $557,750 for a single-family home, which covers the majority of homes in the Phoenix metro area at current prices.
Can You Start with FHA and Switch to Conventional Later?
Yes, and for many Arizona buyers this is the right strategy. If your credit score or financial situation today puts you squarely in FHA territory, getting into a home with an FHA loan is not a permanent decision. Once you have built equity, improved your credit score, and ideally seen your home appreciate, refinancing from FHA to conventional can eliminate MIP entirely and lower your monthly payment.
The refinance makes financial sense when the rate environment is favorable and the new conventional payment, without PMI, is lower than the current FHA payment including MIP. At 20% equity and a 680 or higher score, most borrowers can make the switch profitably. Your lender can run a break-even analysis to show when the refinance pays off based on your actual numbers.
Frequently Asked Questions
Is FHA or conventional better for first-time buyers in Arizona?
What credit score do I need for a conventional loan in Arizona?
How much does FHA mortgage insurance cost in Arizona?
Can I use down payment assistance with an FHA loan in Arizona?
What is the FHA loan limit in Arizona for 2026?
Does the type of loan affect my offer in a competitive Arizona market?
When does it make sense to refinance from FHA to conventional?
Bottom Line: FHA vs. Conventional in Arizona
Choosing between an FHA loan and a conventional loan in Arizona is not about which is better in the abstract. It is about which makes the most financial sense for your specific credit score, down payment, debt load, how long you plan to stay in the home, and the property you are buying in Phoenix, Tucson, Chandler, Gilbert, or wherever you are looking.
FHA gives more Arizona buyers access to homeownership, especially those with lower credit or higher debt. Conventional rewards stronger financial profiles with lower long-term costs and the ability to shed mortgage insurance. Arizona’s Home Plus down payment assistance program changes the math for both loan types and is worth exploring before you rule out either option based on savings alone.
The best next step is to get pre-approved with a lender who can show you both options side by side with your actual numbers. Review the mortgage preapproval checklist to gather your documents in advance, then use a mortgage calculator to compare monthly payments before you walk into that conversation. It is also worth looking at the buyer savings guarantee to understand what additional financial protections may be available to you as an Arizona buyer. Knowing your numbers going in puts you in a much stronger position as a buyer anywhere in the state.